Brazil Implements the SBTI Safe Harbour
On 18 September 2026, Brazil issued IN RFB No. 2,342/2026 to introduce a new framework for the treatment of substance-based tax incentives under its Pillar Two rules.
Article 3.2.3 of the OECD Model Rules applies an arms-length requirement for transactions between constituent entities in different jurisdictions. This should generally apply in any case due to transfer pricing policies under domestic tax laws.
Although these transactions may be eliminated in the consolidated financial accounts, given the Pillar Two GloBE income or loss is based on the entity’s financial accounts they would need to be considered.
If the financial accounts agree to an arms-length basis no adjustment would need to be made unless for tax purposes a different value is used to apply the arms-length basis.
Note that this only applies to the value of intra-group transactions, not the timing of intra-group transactions. Therefore, no adjustment is required to adjust the timing of an item in the financial accounts to the timing under domestic tax law.
The arms-length basis doesn’t generally apply to transactions between group entities in the same jurisdiction, as the jurisdictional blending rules will generally eliminate them anyway. For more information on jurisdictional blending, see ETR calculation and top-up tax.
There are two exceptions to this:
1. a transfer of an asset between group entities in the same jurisdiction that gives rise to a loss that is included in the Pillar Two GloBE income or loss. In this case the arms-length basis needs to be applied otherwise an MNE could artificially manufacture losses.
2. Transactions between a minority-owned constituent entity or investment entity and other constituent entities aren’t subject to the standard jurisdictional blending and their ETR is calculated on a standalone basis. As such the transactions wouldn’t be eliminated in the jurisdictional blending calculation. Therefore, an arms-length requirement applies to these transactions. For more information, see minority-owned entities.
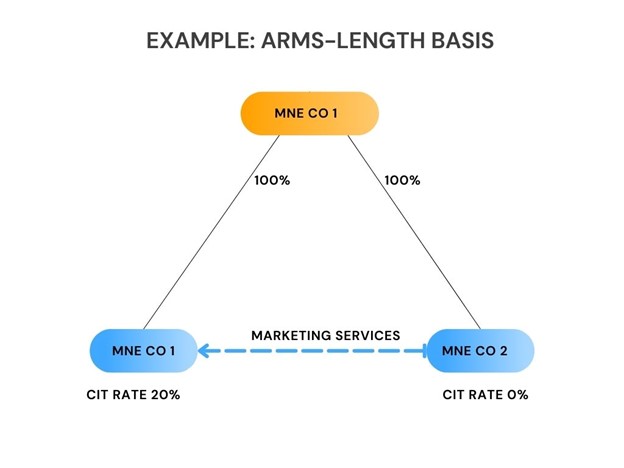
MNECo1 is located in Country A, which has a corporate income tax rate of 20%.
MNECo2 is located in Country B, which has a 0% rate of corporate income tax.
MNECo1 and MNECo2 are both wholly owned by UPE, and this is an MNE group within the scope of Pillar Two.
MNECo2 provided group marketing services to MNECo1. The financial accounts of both MNECo1 and MNECo2 reflect expenses and income of 5,000,000 euros.
However, for tax purposes, MNECo1 deducts 7,500,000 euros.
In this case, 2,500,000 euros is effectively not subject to tax in Country A and is not subject to top-up tax in Country B.
As such, to apply the arms-length requirement MNECo1 is required to add back 2,500,000 euros of its expense for the Pillar Two GloBE income calculation, and MNECo2 is required to reflect additional income of 2,500,000 euros in its Pillar Two GloBE income calculation.
Adjustments can also apply when there is a unilateral transfer pricing adjustment.
For instance, if in the above example MNECo1 had deducted an expense of 3,000,000 euros for tax purposes as a result of a unilateral transfer pricing adjustment, this would increase taxable income subject to corporate income tax by 2,000,000 euros in MNECo1, but that 2,000,000 of income is also subject to top-up tax in MNECo2.
Therefore, MNECo1 is required to reduce its expense in the calculation of Pillar Two GloBE income by 2,000,000 euros and MNECo2 is required to reduce its Pillar Two GloBE income by 2,000,000 euros.
Note that if the result of an adjustment to the arms-length basis would result in double taxation or non-taxation, then no adjustment is made.
For instance, if in the example above MNEco2 reflected income of 4,000,000 euros for tax purposes and the corporate income tax rate was 10%, no adjustment would be required.
Although the deduction in MNECo1 is 5,000,000 euros, this is included in Pillar Two GloBE income and is subject to top-up tax in MNECo2. Therefore, no adjustment is permitted.

On 18 September 2026, Brazil issued IN RFB No. 2,342/2026 to introduce a new framework for the treatment of substance-based tax incentives under its Pillar Two rules.

On 15 September 2026, the Dutch government presented a bill that would introduce four new Pillar Two safe harbours, extend the Transitional Country-by-Country Reporting Safe Harbour and amend the treatment of certain 52- and 53-week accounting periods.
On September 11, 2026, the OECD released a package of guidance and implementation materials that provides for the exclusion of Explicitly Conditional Taxes from Covered Taxes, clarifies the treatment of mismatched fiscal periods under the Qualified Domestic Minimum Top-up Tax Safe Harbour, updates the GloBE Information Return and establishes the detailed framework for full legislative reviews of domestic minimum tax rules.
Uruguay’s presidential decree dated 31 August 2026 replaces the conditional QDMTT payment waiver in Decree No. 325/025 with a compensation mechanism. Article 1 requires in-scope constituent entities allocated QDMTT in Uruguay to comply with its QDMTT obligations and pay the tax; article 7 repeals the earlier decree.
Qatar has published six decisions dealing with currency conversion, simplified reporting, the Transitional CbCR Safe Harbour, non-material constituent entities, designated local entities and registration.
The Slovak Government has approved draft legislation that would make significant changes to Slovakia’s qualified domestic minimum top-up tax regime. The proposals would implement the OECD’s new Substance-Based Tax Incentives Safe Harbour, extend the Transitional CbCR Safe Harbour and introduce rules preserving Pillar Two filing and payment obligations where a Slovak taxpayer ceases to exist without a legal successor.
Cyprus has opened a public consultation on amendments to its Pillar Two legislation intended to address observations from the European Commission and align the domestic rules more closely with OECD guidance. The consultation opened on 30 July 2026 and is scheduled to close on 5 September 2026.
On August 7, 2026, Germany published a regulation that gives domestic legal effect to a jurisdiction-by-jurisdiction list of qualifying Pillar Two jurisdictions.
On August 8, 2026, Mauritius issued its QDMTT regulations to implement its QDMTT.
| Cookie | Duration | Description |
|---|---|---|
| cookielawinfo-checkbox-analytics | 11 months | This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics". |
| cookielawinfo-checkbox-functional | 11 months | The cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional". |
| cookielawinfo-checkbox-necessary | 11 months | This cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary". |
| cookielawinfo-checkbox-others | 11 months | This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other. |
| cookielawinfo-checkbox-performance | 11 months | This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance". |
| viewed_cookie_policy | 11 months | The cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data. |